A machinery insurance claim ultimately rests on a technical question — what actually happened, and why — and insurance engineering is the discipline that answers it with evidence rather than assumption.
Executive Summary. Insurance engineering is the application of independent technical assessment to industrial machinery damage claims. Where a repair quotation answers "what will it cost to fix," insurance engineering answers a different, prior set of questions: what actually caused the damage, how extensive is it, is the asset repairable, and what would a technically sound and commercially reasonable recovery scope look like. This guide explains what insurance engineering involves, the technical questions it addresses, how it differs from a standard repair assessment, and how it connects to root cause analysis and Recovery Cost Estimation — and serves as the central reference point for SRT's articles on RCA and machinery claims.
What Insurance Engineering Actually Means
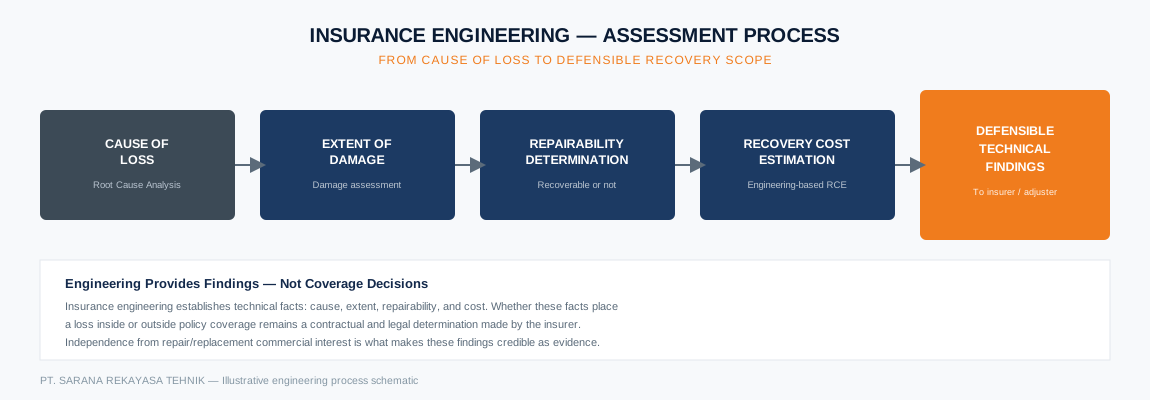
Insurance engineering is the application of independent, evidence-based technical assessment to industrial machinery damage — specifically structured to support the questions that arise when that damage is the subject of an insurance claim. It sits at the intersection of engineering investigation and insurance claims practice, providing the technical foundation on which claims decisions are made, without making those decisions itself.
This distinction matters: an insurance engineer's role is to establish technical facts — cause, extent, and repairability — from an engineering perspective. Whether those facts place the loss inside or outside policy coverage is a contractual and legal determination made by the insurer, not a conclusion the engineering assessment itself reaches.
The Core Technical Questions Insurance Engineering Answers
| Question | Why It Matters to the Claim |
|---|---|
| What is the cause of loss? | Establishes whether the triggering event was sudden and external, or gradual and potentially excluded (e.g., wear, inadequate maintenance) |
| What is the pre-loss condition? | Establishes the asset's baseline condition before the incident, relevant to distinguishing new damage from pre-existing condition |
| What is the post-loss condition? | Documents the actual extent of damage across all affected systems, not only the most visible component |
| Is the asset repairable? | A technical determination of whether recovery is achievable to safe, functional condition — distinct from a total loss determination |
| What would defensible recovery cost? | An engineering-based Recovery Cost Estimation, built from actual scope of work rather than assumption |
Each of these questions requires physical evidence, testing, and engineering reasoning — not visual impression. This is the same evidentiary standard covered in Root Cause Analysis: A Practical Engineering Approach →, which addresses the "cause of loss" question in particular depth.
Insurance Engineering vs. a Standard Repair Assessment
A repair contractor's assessment and an insurance engineering assessment can look superficially similar — both involve inspecting a damaged machine — but they differ in purpose, independence, and evidentiary standard.
- Independence. A repair contractor typically has a commercial interest in the scope and cost of the repair being approved. An insurance engineering assessment is conducted without that direct interest, strengthening its credibility as evidence.
- Scope of inquiry. A repair assessment usually asks "what needs fixing." An insurance engineering assessment additionally asks "why did this happen" and "was this event or condition the actual cause" — questions a repair quotation does not need to answer.
- Documentation standard. Insurance engineering findings are documented to a standard intended to withstand scrutiny — from the insurer, a counter-assessment, or in some cases legal proceedings — not simply to justify a cost.
Key Components of an Insurance Engineering Assessment
Damage Assessment and Classification
Physical inspection, testing, and documentation of the actual extent of damage across all affected systems — mechanical, electrical, structural — establishing a factual record independent of the eventual repair scope.
Root Cause Analysis
Structured investigation into why the failure occurred, distinguishing root cause from symptom and failure mechanism, and identifying whether the cause was sudden and external or gradual and condition-related. See Root Cause Analysis: A Practical Engineering Approach → and Root Cause Analysis: The Key to a Strong Machine Insurance Claim → for detailed treatment of this component.
Repairability Determination
An engineering judgment on whether the asset can be technically and economically restored to safe, functional condition, based on assessment findings rather than assumption or the asset's age alone.
Recovery Cost Estimation
Where repair is technically supported, an itemized, engineering-based cost estimate — covering labor, materials, testing, and commissioning — built from the actual scope of damage rather than a percentage of asset value. Covered in depth in Beyond Cost Estimation: The SRT RCE Principle →.
Related Concepts in Insurance Engineering
Several terms commonly appear alongside insurance engineering assessments. From an engineering perspective, these are worth distinguishing:
- Betterment refers to an improvement beyond the asset's pre-loss condition introduced during repair — for example, upgrading to a higher-specification component than what failed. Whether betterment affects claim settlement is a policy matter, but identifying where betterment exists is an engineering observation.
- Depreciation reflects the reduction in an asset's value due to age and prior wear, independent of the specific loss event — again a valuation and policy consideration informed by, but not determined by, engineering findings.
- Salvage refers to any remaining value in damaged components or the asset itself, relevant where replacement rather than repair is the outcome.
- Business interruption considerations — while primarily a financial and operational matter — are often informed by the engineering estimate of realistic recovery timeline.
SRT's role in each of these areas is to provide the underlying engineering facts and reasoning — not to render the legal or contractual conclusion that follows from them.
Who Relies on Insurance Engineering
Insurance engineering assessments are typically commissioned by, or relied upon by, several parties across the claims process: insurance companies evaluating a claim, loss adjusters managing the claims process, insurance brokers advising policyholders, risk engineers assessing exposure, and asset owners substantiating their own claim or evaluating recovery options independently of the insurer's process.
The Evidentiary Standard: Why It Matters
A claim supported by findings that are traceable to specific physical evidence, test results, and documented reasoning is materially more defensible than one supported by visual inspection and general impression. This is true regardless of which party commissions the assessment — an insurer seeking to validate a claim and a policyholder seeking to substantiate one both benefit from evidence that can withstand independent scrutiny.
This is the same principle underlying SRT's broader technical assessment approach: findings should distinguish clearly between confirmed fact, engineering judgment, and assumption — and should state explicitly where further testing would be required to resolve remaining uncertainty, rather than presenting a conclusion with unstated caveats.
Key Takeaways
- Insurance engineering provides independent technical findings — cause of loss, extent of damage, repairability — it does not determine claim coverage, which remains a policy and legal matter.
- Independence from repair or replacement commercial interest is what makes insurance engineering findings credible as evidence.
- Root Cause Analysis and Recovery Cost Estimation are core technical components feeding into a complete insurance engineering assessment.
- Concepts like betterment, depreciation, and salvage are informed by engineering findings but are ultimately policy and valuation determinations.
- The evidentiary standard — traceable, documented, evidence-based findings — matters regardless of which party commissions the assessment.
Need an independent technical assessment to support a machinery insurance claim? SRT's engineering team can conduct damage assessment, root cause analysis, and Recovery Cost Estimation to an evidentiary standard.
Frequently Asked Questions
What is insurance engineering?
Insurance engineering is the application of independent technical assessment to industrial machinery damage claims — determining cause of loss, extent of damage, and repairability from an engineering perspective, to support the insurance claims process with objective evidence.
Does an insurance engineer decide whether a claim is covered?
No. An insurance engineer provides technical findings — cause of loss, extent of damage, and repairability — from an engineering perspective. Coverage determination is a policy and legal matter decided by the insurer, not the engineering assessment itself.
What is the difference between a loss adjuster and an insurance engineer?
A loss adjuster manages the overall claims process, including policy interpretation and settlement. An insurance engineer provides the independent technical findings — such as root cause and damage assessment — that inform the loss adjuster's evaluation of the claim.
Why does an insurance claim need independent technical assessment?
Independent technical assessment provides objective, evidence-based findings on cause and extent of damage, which is more defensible than a report from a party with a direct interest in the claim outcome, such as the repair contractor.
What does repairability assessment mean in an insurance context?
Repairability assessment is the engineering determination of whether a damaged asset can be technically and economically restored to safe operating condition, as distinct from being deemed a total loss — this determination should be based on technical assessment, not assumption.
Explore the Insurance Engineering Series
What technical evidence actually strengthens a claim, and red flags to watch for.
What to gather, and when, to build a defensible claim.
Why weak investigation reports get insurance claims rejected.
The investigation process, methodologies, and evidence standard behind a defensible RCA.
How a defensible Recovery Cost Estimate is built for insurance and audit purposes.
The broader recovery decision framework this cluster connects to.
Why gradual damage causes need different insurance treatment than sudden events.
The complete engineering decision framework closing out this series.